SpaceX Low-Band Spectrum Move Shakes Wall Street as Starlink Mobile Targets Up to 13% US Wireless Market Share
NEW YORK — Recent strategic spectrum acquisitions by aerospace operator SpaceX have triggered mounting volatility across Wall Street, raising structural questions surrounding the long term market dominance of the traditional United States telecommunications oligopoly and introducing unforeseen downstream risks for consumer device hardware makers including Apple.
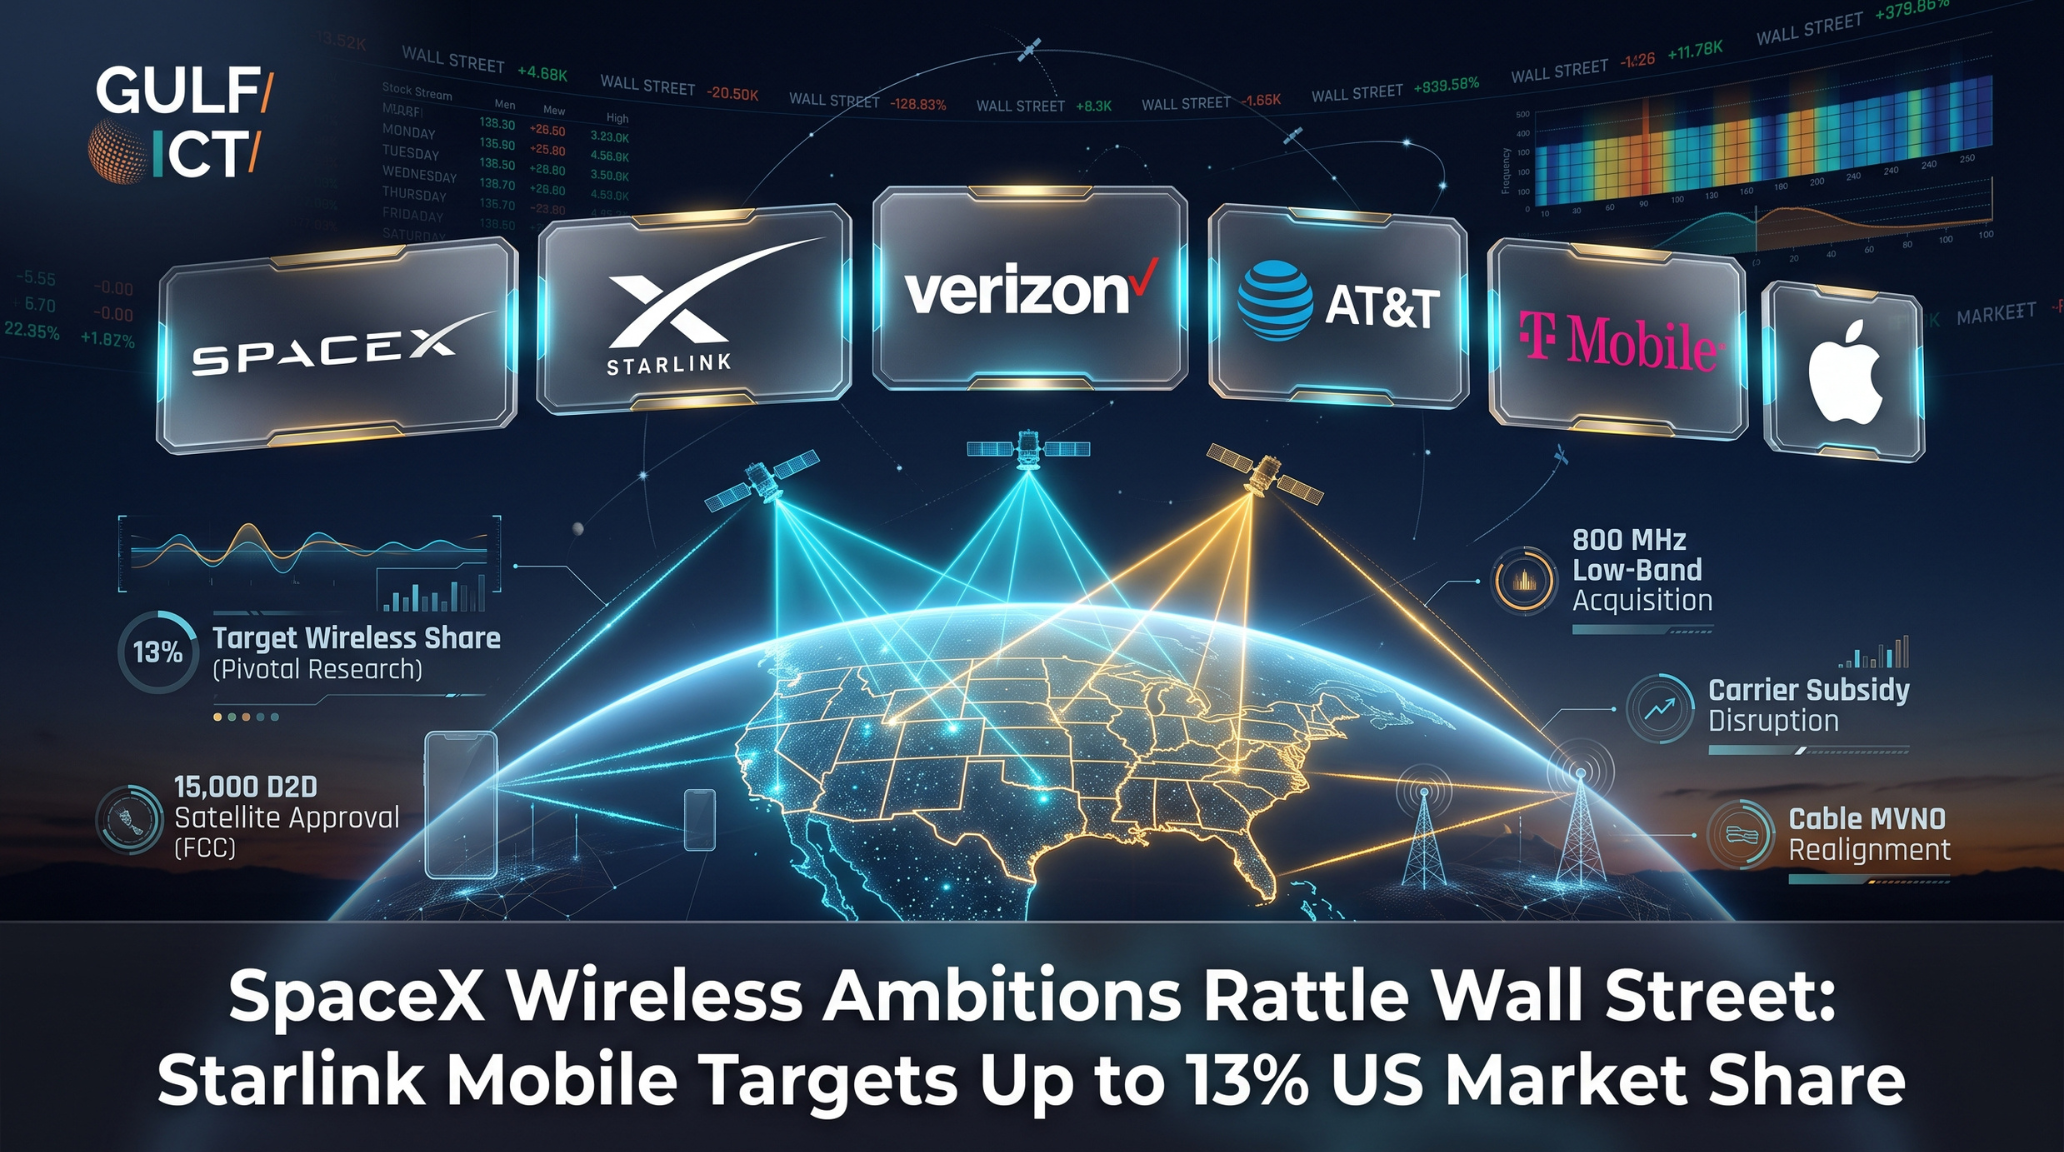
The competitive disruption follows SpaceX’s announced acquisition of nationwide low band 800 MHz spectrum licenses, a development that temporarily erased billions of dollars in aggregate equity capitalization across the three incumbent wireless carriers, namely Verizon, AT&T, and T Mobile. While share prices subsequently experienced a partial technical recovery, financial markets are actively pricing in the viable emergence of a disruptive fourth national facilities based or hybrid wireless carrier.
Financial projections underscore the potential scale of the disruption. Jeffrey Wlodarczak, equity research analyst at Pivotal Research, projected that SpaceX’s Starlink unit could capture as much as 13 percent of the US wireless market within the next decade, describing Elon Musk’s aggressive asset assembly as the foundation of a legitimate fourth national carrier designed for eventual global export. Concurrently, regulatory momentum is accelerating after the Federal Communications Commission (FCC) granted SpaceX authorization to operate an expanded constellation of 15,000 direct to cell satellites, accompanied by a specialized regulatory waiver allowing transmissions to bypass legacy terrestrial cell towers entirely.
Market strategists indicate that while deploying full terrestrial network density across metropolitan cores requires vast capital expenditure, SpaceX can execute a phased expansion by first deploying service across rural and exurban peripheries where its established consumer satellite broadband subscriber base already resides.
Institutional analysts outline several strategic pathways. Analysts at Evercore ISI highlight that leading cable multi system operators such as Charter Communications and Comcast could emerge as natural joint venture partners or aggressive competitors, noting that any formal integration between cable mobile virtual network operators (MVNO) and orbital infrastructure would constitute a seismic industry realignment. Conversely, analysts at Bank of America anticipate defensive countermoves from incumbent telcos, including aggressive bundling of home fiber broadband with mobile lines to reduce consumer churn by as much as 50 percent.
The disruption extends into consumer electronics ecosystems. Bank of America equity analysts caution that if SpaceX constructs a vertically integrated consumer ecosystem combining non terrestrial carrier services with proprietary hardware, it could fundamentally destabilize the longstanding carrier device subsidy model that historically underwrites retail purchases of Apple’s premium iPhone lineup.
Meanwhile, analysts at TD Cowen suggest the aggressive spectrum purchase could also function as commercial leverage in high stakes negotiations, positioning SpaceX to extract lucrative wholesale terms for a nationwide hybrid MVNO agreement with one of the established terrestrial wireless giants.